A Loan “Taken Out on Grandma”
After a long conversation with Ms. Ewelina, I learned the circumstances of her case. Ms. Ewelina had helped her family in Poland all her life. First her daughter needed money for an apartment, then her sister for a car. Every year there were holidays, birthdays, anniversaries and First Communions, for which Ewelina sent packages and cash. When she last visited her family, her grandson was starting a business and badly needed money. Ewelina didn’t have cash with her, so she agreed to her grandson’s proposal to take out a bank loan together with him. The grandson did not have a steady job, so he would not have gotten a bank loan on his own. The bank approved the application because Ewelina had Polish documents, a Polish address and a steady income – her pension from ZUS (Poland’s Social Insurance Institution). In addition, Ewelina had no other loans anywhere in Poland, which the bank checked thoroughly.
Ewelina returned to the US. Six months later, letters of some sort began arriving at Ewelina’s Polish address. When her sister called about them, Ewelina told her to set the letters aside, because she would look through them when she came to Poland again. A few months later, to Ewelina’s surprise, the pension paid by ZUS dropped from PLN 2,250 to about PLN 1,680.
The Bank Collects Its Debts
Ms. Ewelina’s grandson used the loan to open a store. He quickly found out that the business was losing money and he had nothing to pay the installments with. Here is what happens in such a case.
60 days after the debt becomes overdue, the bank sends the debtor a registered letter, so that it has proof that it demanded payment. In the letter, the bank informs the debtor that if payment is not made, it may put the debtor on a blacklist of debtors (if the debt is larger than PLN 200). The family signed for the letter on Ms. Ewelina’s behalf. After 90 days, the debt is recorded in the Biuro Informacji Kredytowej (BIK, Poland’s credit bureau), which means you cannot use any form of installment buying or cell phone and TV subscription plans. But that is just the beginning.
A Payment Order for the Bank
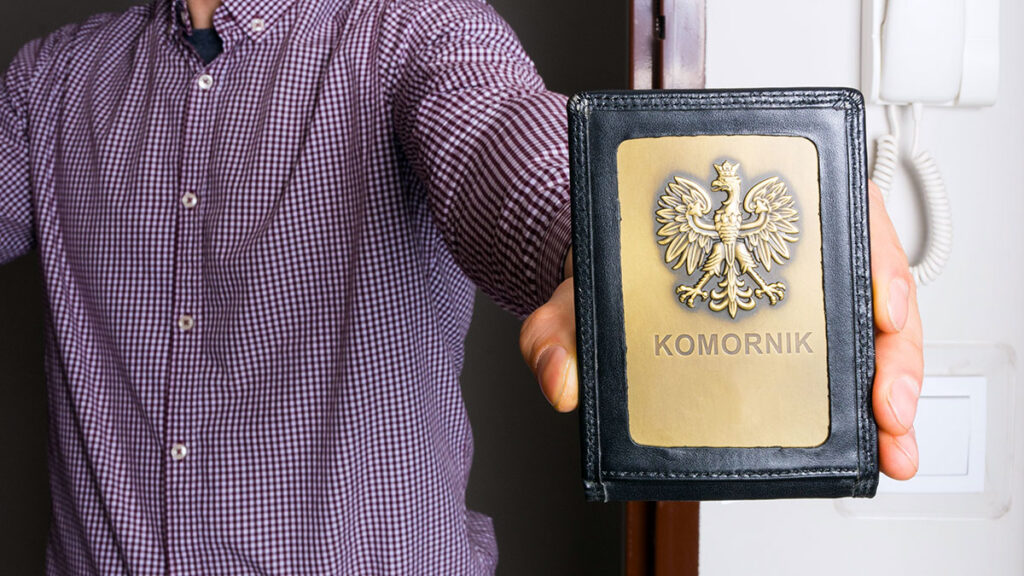
The bank applies to the court for a payment order, using a simplified procedure. The court issues the order automatically, checking only whether the debt exists according to the paperwork, that is, the contracts and invoices. The court serves the payment order on the defendant together with the claim and attachments, ordering him or her to satisfy the claim with costs within a specified time from the date the payment order is served. If the debtor disagreed with the order, the court would schedule a hearing at which any doubts would be examined. But Ms. Ewelina did not read the court papers and did not respond to the court, so the judgment became final. The bank hired a komornik (court bailiff), who asked ZUS to garnish the pension.
Garnishment of the Pension by a Bailiff
Borrowing “on Grandma” or “on Grandpa” is becoming a plague in Poland. Many people of retirement age appear in debtor registries. The debts involve cash loans from banks and lending companies, contracts with telecom operators and installment purchases. Disability pensioners and retirees have a steady income, so the bank sees them as creditworthy, unlike grandchildren, nephews or nieces with no creditworthiness.
How Much the Bailiff Will Take
A bailiff cannot seize the entire retirement or disability pension, no matter how many loans and creditors the retiree has.
For debts other than child or spousal support, the bailiff can take a maximum of 25% of the retirement or disability pension, and must leave the retiree an amount that is exempt from enforcement. As of March 1, 2026, the minimum retirement pension, disability pension for total incapacity to work and survivors pension is PLN 1,978.49, and the amount exempt from enforcement of debts other than support is PLN 1,401.57. These amounts change every year on March 1, with the annual cost-of-living adjustment of benefits.
Note: If, after deducting the health insurance contribution and income tax due, the benefit is lower than the amount exempt from deductions, the bailiff cannot carry out enforcement. Also, by law, the bailiff cannot seize either the “trzynastka” or the “czternastka” (the additional annual pension payments). Indebted people can use this additional benefit themselves to pay off their debts.
The Statute of Limitations
Can the statute of limitations help? An indebted senior can defend himself or herself by raising the objection that the debt is time-barred, that is, a debt the creditor has not pursued for a long time. Since 2018, the general limitation period in Poland has been six years, and for claims for periodic payments and claims related to running a business – three years; in addition, the period ends on the last day of the calendar year. In practice, in Poland a debt for a purchased item becomes time-barred after two years, a bank’s claims under a loan agreement – after three years, personal loans – after six years, apartment rental and periodic claims (for example, a phone subscription) – after three years, tax liabilities – five years from the end of the calendar year in which the tax payment was due.
The limitation period can be interrupted, for example, by the creditor or a debt collection company filing a lawsuit, filing a request with a bailiff to begin enforcement, filing a request for an enforcement clause to be attached to an enforcement title (for example, a court judgment), or acknowledgment of the debt by the debtor, which can be, for example, signing an agreement with a debt collection company in which the debtor undertakes to repay the debt.
If the bank had not pursued Ms. Ewelina for repayment of the loan for three years, the debt would have become time-barred. But it did, and it obtained a payment order, so the statute of limitations is out of the question.
What Should Have Been Done?
First of all, Ms. Ewelina should not have taken out a loan for her grandson, who is an adult and should manage on his own. But now it’s after the fact.
Would Ms. Ewelina have achieved anything if she had responded to the court papers? Not necessarily. The debt is a fact, and she has nothing in her defense, because the failure of her grandson’s business is not a mitigating circumstance. Ewelina’s name and signature are on the loan agreement, and her grandson is insolvent, so she has been held liable. A court hearing would only have dragged out the procedure and added extra costs.
What is the advice? Ms. Ewelina has no choice but to repay the loan. Information about the loan not repaid on time will remain in the Polish credit bureau BIK for 5 years.
Updated October 2026.